What's usually covered
Property insurance commonly covers sudden, accidental damage from perils such as wind, hail or falling trees, subject to your deductible and policy terms. Gradual deterioration, lack of maintenance and long-term leaks are commonly excluded. The Insurance Information Institute explains these concepts in plain English. Always read your own policy.
Document the damage
- Date and time of the storm; save weather alerts
- Photos and video inside and out (only go on the roof if safe)
- Damaged contents and interior finishes
- Receipts for emergency work and materials
Mitigate further damage
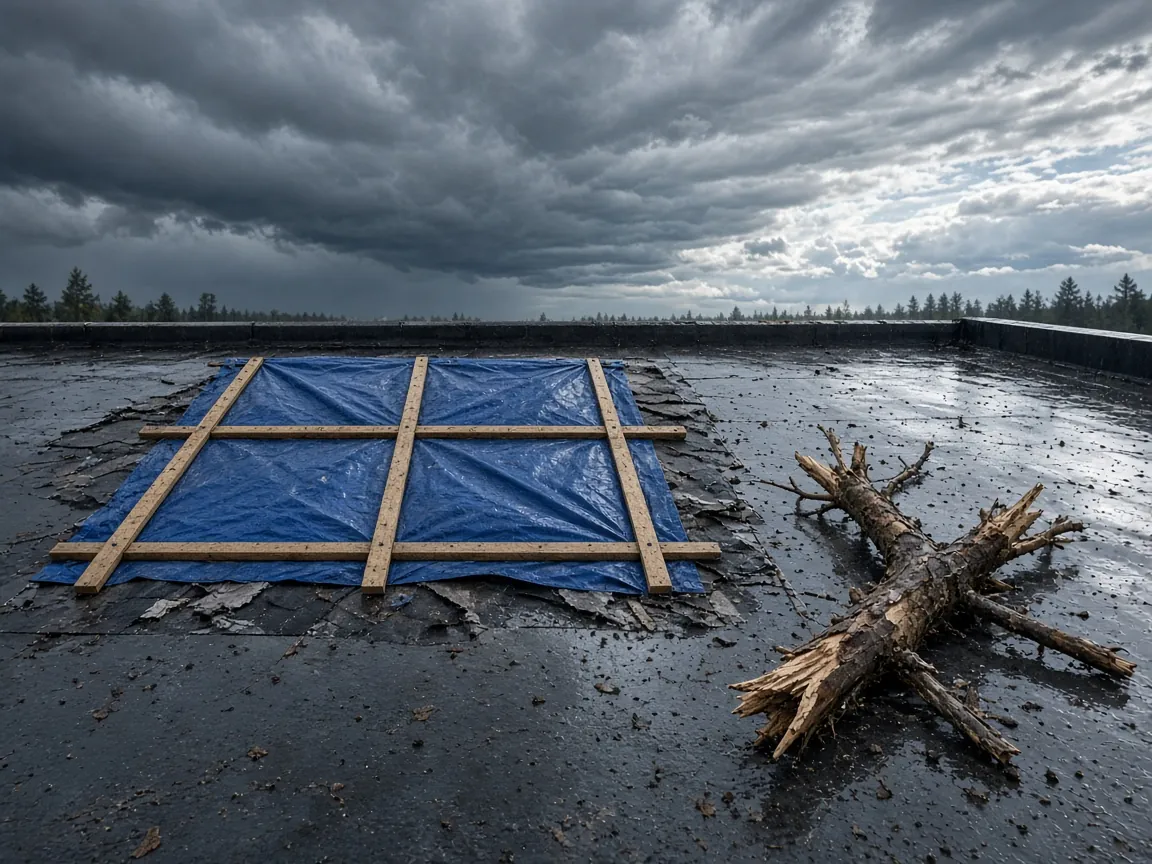
Most policies expect reasonable steps to prevent further damage, such as tarping or temporary patches. Keep the damaged materials or photos of them until the adjuster has seen them.
Working with the adjuster
- Have your roofer's written assessment with photos ready.
- Point out all damage, including flashing and edge metal.
- Ask how matching, code upgrades and wet insulation are handled.
- Be cautious with anyone offering to "cover your deductible"; in many states that's illegal.